PFA
FINANCIAL ANALYTICS

SBA acquisition analysis for loan brokers, prepared to an underwriter's standard.

PFA Financial Analytics works as the analysis arm of your brokerage. I prepare the earnings recast, the coverage test and the lender package for SBA 7(a) acquisitions, delivered under your firm's name.

DEALS
SBA 7(a) business acquisitions, roughly $250k–$3M purchase price
STANDARD
SOP 50 10 8.1: 1.25x on adjusted historical earnings
TURNAROUND
Screening in 48 hours. Full package in 3–5 business days
DELIVERY
White-label, under your firm's name
Send a deal for a free screening See a complete sample package
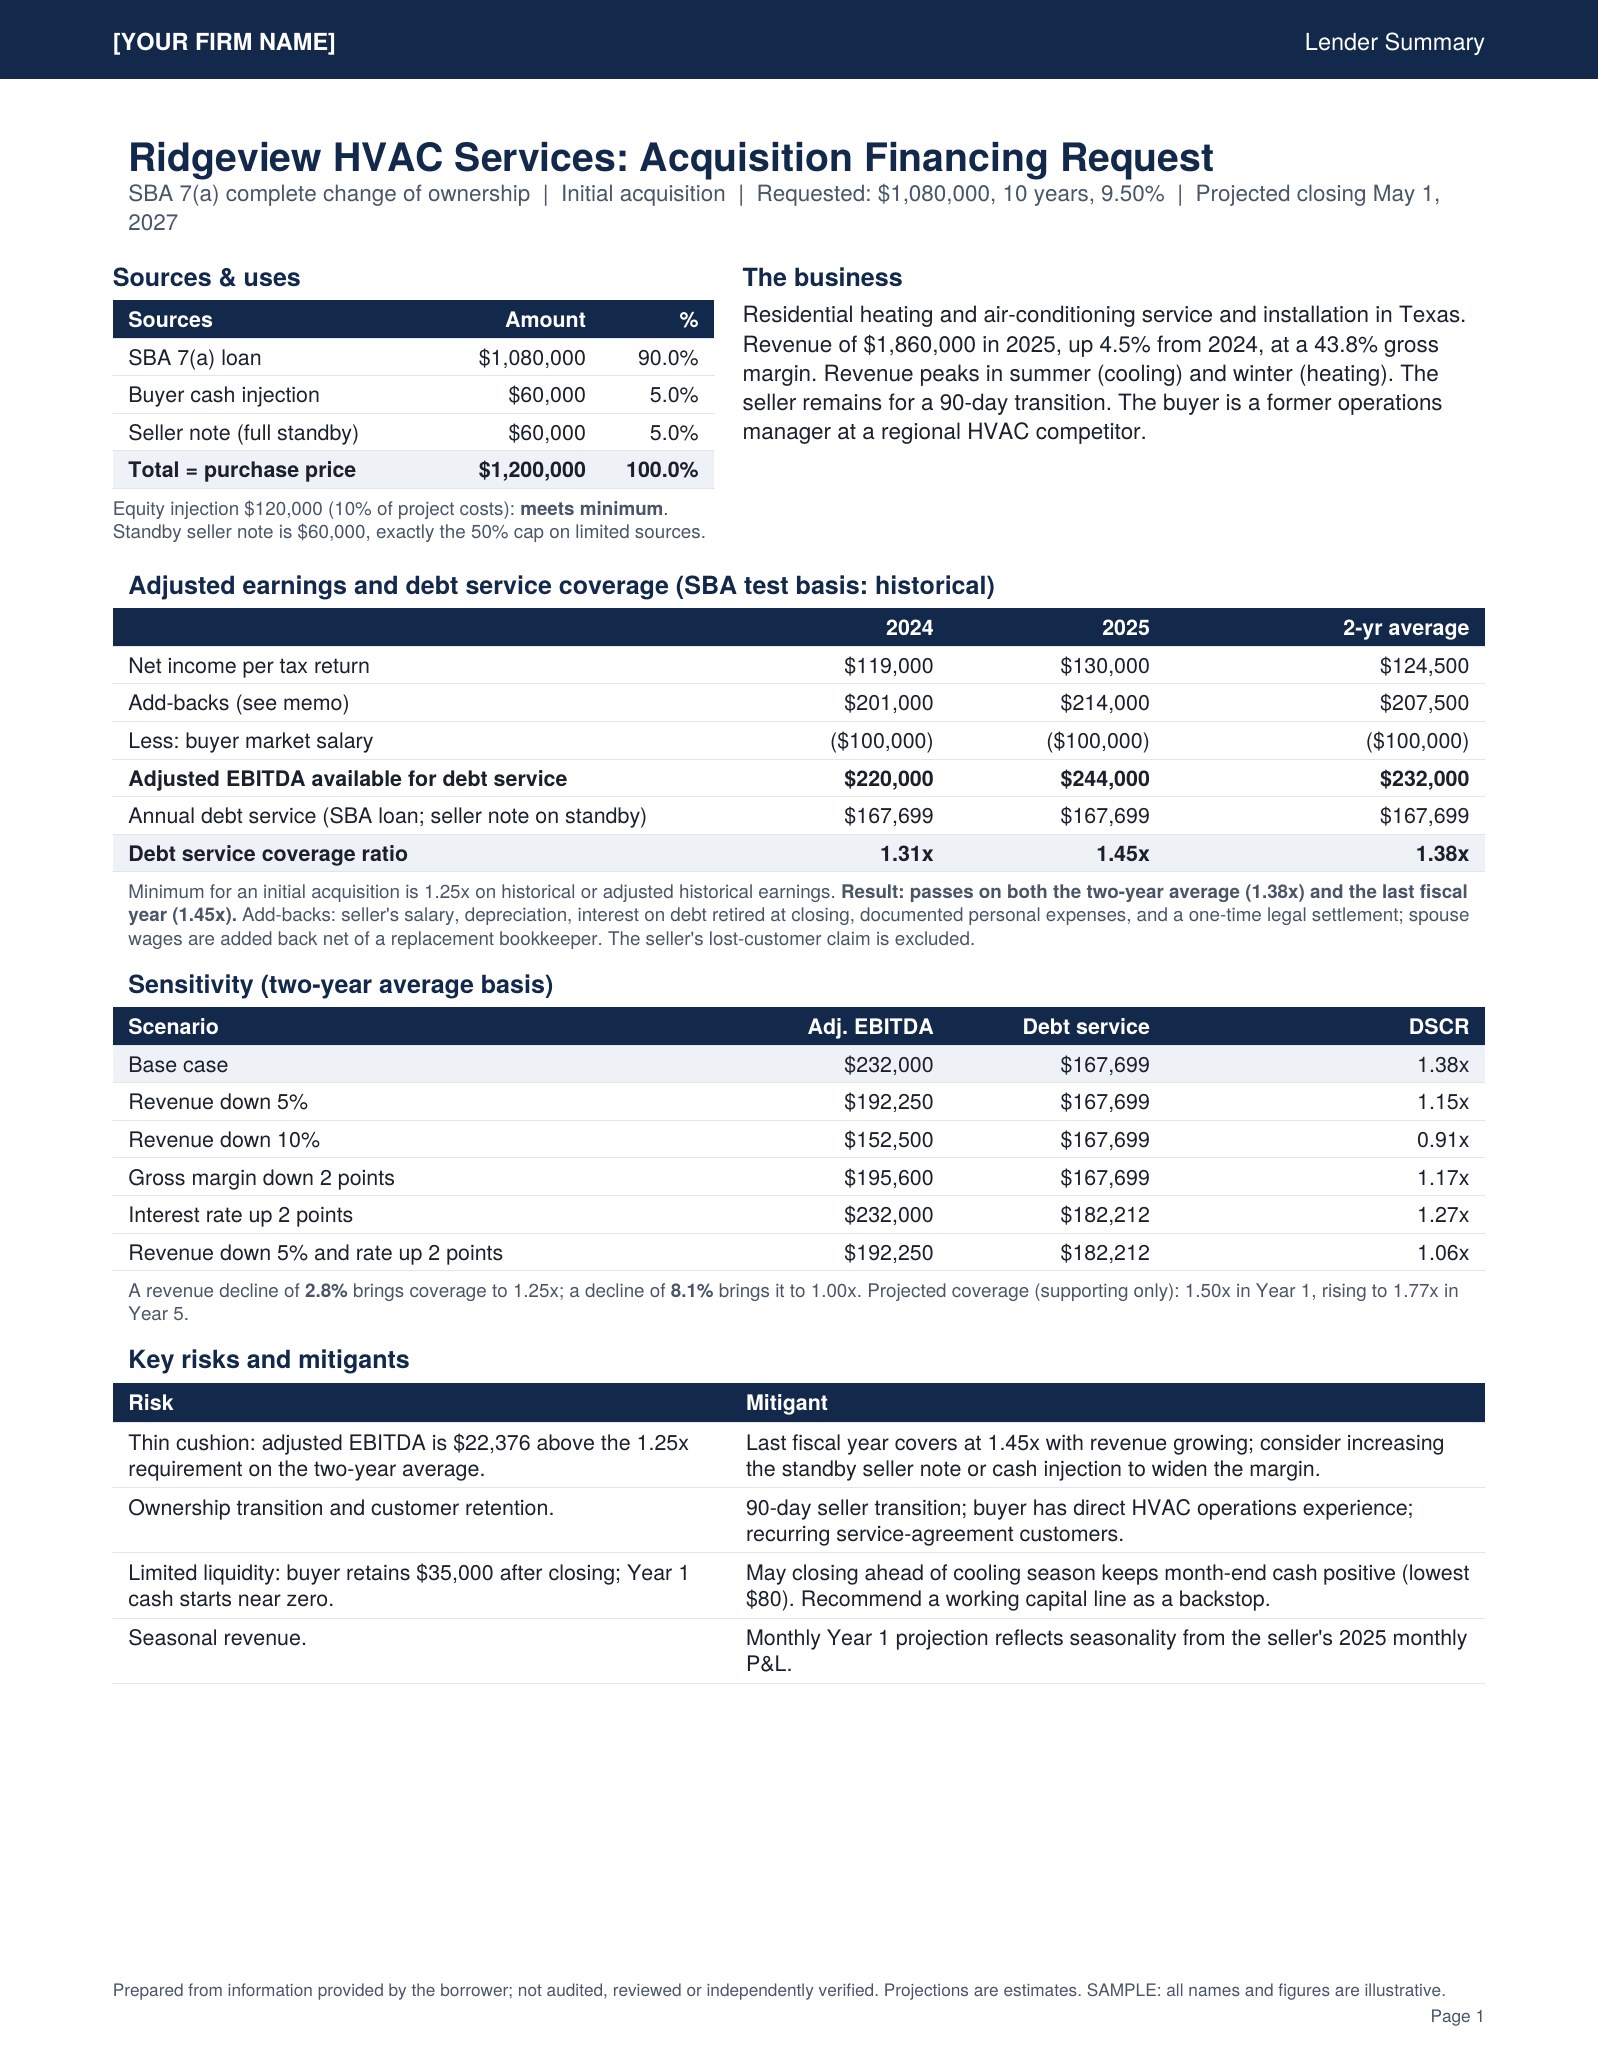
Page 1 of a sample lender summary for a fictional HVAC acquisition
Page 1 of a sample lender summary (fictional deal). View the full package

The sample deal at a glance

See the full sample package
$1.2M
Purchase price, SBA 7(a) acquisition
1.38x
Coverage on the two-year average, against 1.25x required
2.8%
Revenue decline before coverage hits the 1.25x floor
3–5 days
From a complete file to a lender-ready package
Ridgeview HVAC is a fictional company. The method and the checks are the ones used on live files.

What I check on every file

Since October 1, acquisitions are approved on last year's numbers. These are the points an underwriter tests, checked before your file goes in.

  1. 01
    Revenue against bank deposits
    Reported sales reconciled to deposits for the trailing period and both fiscal years.
  2. 02
    Every add-back and its support
    Each one accepted, reduced or rejected, with the document it rests on.
  3. 03
    A market salary for the buyer
    Deducted before coverage is measured, as lenders do.
  4. 04
    Costs that change at closing
    Lease resets, roles that must be replaced, insurance and benefits.
  5. 05
    Customer concentration
    Share of revenue from the largest accounts and how it has moved.
  6. 06
    The transaction category
    Initial acquisition, expansion or buyout under SOP 50 10 8.1, and the coverage floor that applies.
  7. 07
    Equity injection sources
    Buyer cash against standby seller debt and other limited sources, within the 50% cap.
  8. 08
    Debt service on the real structure
    Term, rate, standby notes and any debt assumed or retired.
  9. 09
    Stress cases
    Revenue and margin declines, rate increases, and the break-even point for 1.25x and 1.00x.
  10. 10
    Liquidity after closing
    Buyer reserves and month-by-month cash in a seasonal first year.

What you receive

DELIVERABLE CONTENTS FORMAT
Lender summary One page: structure, adjusted earnings, coverage, stress results and risks with mitigants. PDF and Word
Financial model Recast, sources and uses, debt schedule, coverage test, five-year projections, Year 1 by month, stress tests and integrity checks. Editable Excel
Assumptions memo A written explanation of every add-back and assumption, ready for the underwriter. PDF and Word
Underwriter questions Written answers to lender follow-ups on the file. Within one business day

Everything carries your firm's name and branding. File properties are cleared. See the sample package

How an engagement works

  1. Send the deal. Letter of intent, three years of business tax returns, interim statements and the seller's add-back list, through a secure upload link.
  2. Free screening. Within 48 hours: estimated adjusted earnings, coverage against 1.25x, and the issues an underwriter will raise.
  3. Full package. If the deal works, the model, summary and memo follow in 3–5 business days.
  4. Underwriting. Forward lender questions and I answer them in writing.

Services

Core

  • Deal screening
    A fast read on a live deal before it goes to a lender. The first one is free.
  • SBA acquisition package
    Recast, model, lender summary and assumptions memo.
  • Startup and expansion projections
    Lender-ready projections where historical earnings don't exist yet.

Also available

  • Listing financial packages
    For business brokers: a recast and SBA financeability check on a listing.
  • Earnings normalization
    A standalone add-back analysis from tax returns.
  • Financial statement spreading
    Messy statements put into a consistent, lender-standard format.
  • Model and package review
    A second read of an existing model before submission.
  • Cash flow forecasting
    Monthly and 13-week forecasts for new owners after closing.
  • Custom models and tools
    Structuring models and Excel tools for advisory teams.

Fixed pricing per package. Ask for the rate sheet.

Your analysis arm

Think of PFA as your firm's in-house analysis team, without the hire. You keep the client and the lender relationship; I build the numbers behind them, under your name.

Every file is prepared and reviewed by me, Steve, a financial analyst with 3 years of experience in financial modeling and analysis.

You deal with one person from intake to the underwriter's last question. No handoffs, no offshore team, no templates filled in by someone who has never read the SOP.

  • Replies within one business day
  • Everything in writing, ready to forward to the underwriter
  • Confidentiality agreement signed on request

Confidentiality

  • Documents arrive by secure upload link, never as email attachments.
  • Please redact Social Security numbers before uploading.
  • Client files are deleted 30 days after delivery.
  • I never contact your client or their lender. Any disclosures SBA rules require about who helped prepare a package remain yours to make.

Terms of Service · Privacy Policy

Notes

NOVEMBER 2026
What changed for SBA acquisition loans on October 1, and what it means for your files
The coverage floor, the end of projections as support for approval, mandatory valuations, and the new limits on equity sources.
Read the note

Have a live acquisition?

Send it for a free screening. Within 48 hours you'll have adjusted earnings, the coverage test and the issues an underwriter will raise.

Start a screening [email protected]